
One Card Instead of Ten: What You Can Do With a Digital Identity Card in 2026
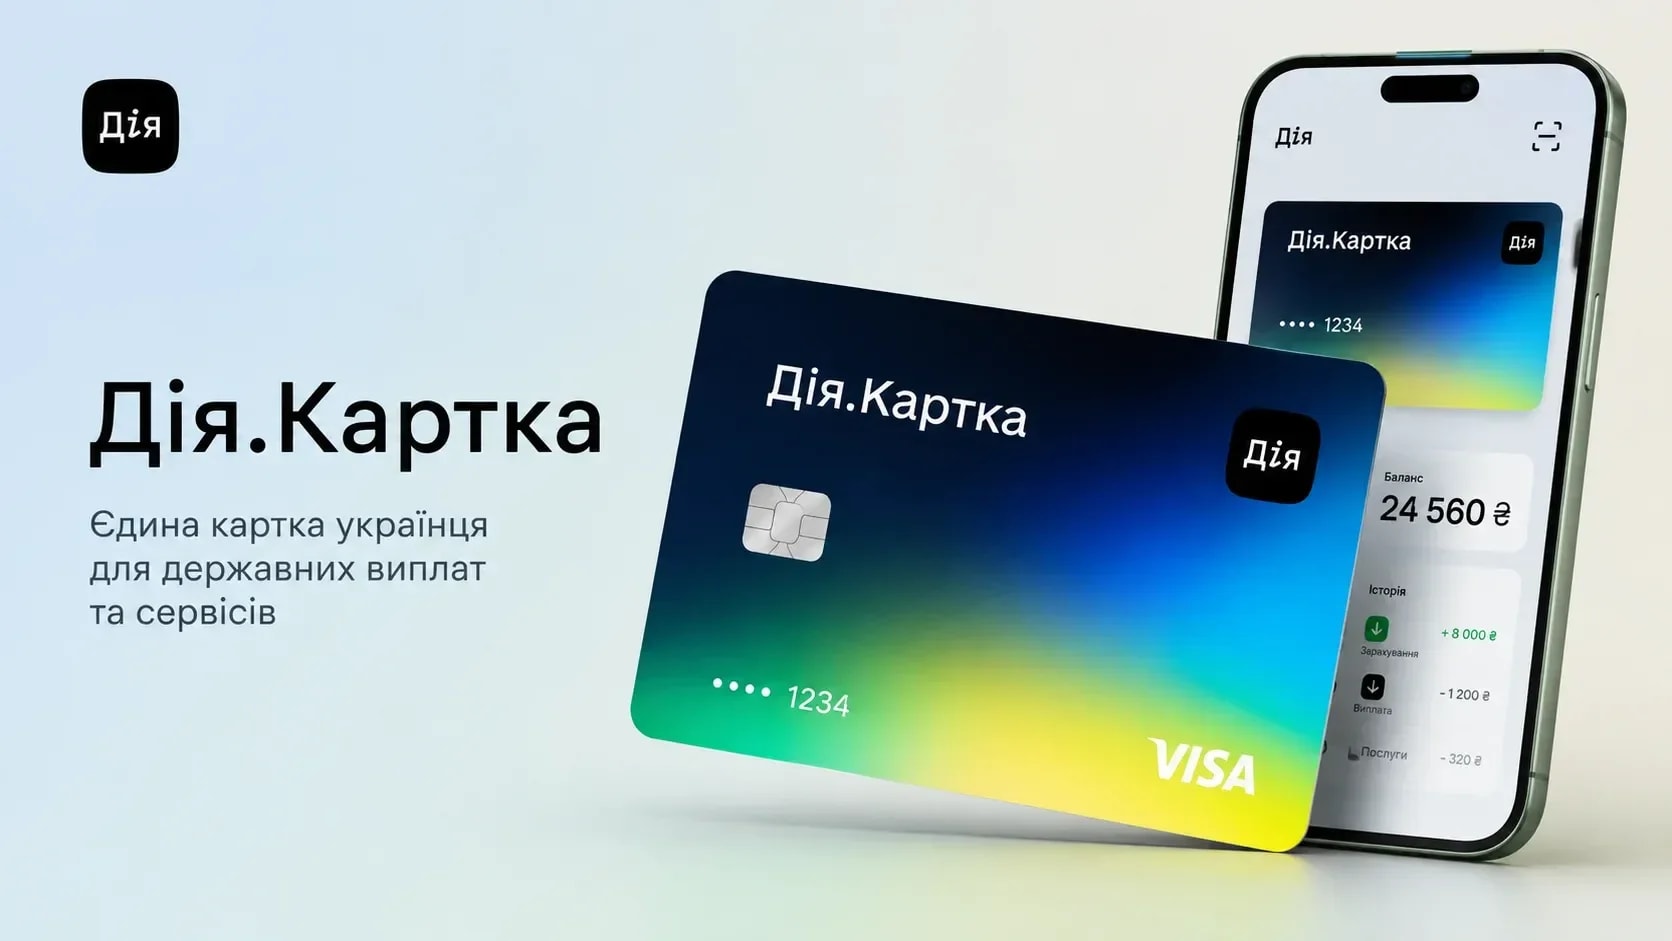
A search for a digital identity card can lead to several different products, but Ukraine's Diia.Card is not a generic electronic ID. It is a bank card designed to receive and manage payments from multiple state programs through one payment instrument. The identity and government-service side is handled through Diia, while the actual card account is opened and serviced by a partner bank.
Contents14
- What Diia.Card is and why it differs from a digital identity card
- Why Diia.Card already has more than 5.8 million users
- What payments go to Diia.Card in 2026
- What is the Child Care Account
- Diia.Card and the "Baby Package": how the payment works
- Does the school kit ("Schoolboy Package") go to Diia.Card
- How Screening 40+ works through Diia.Card
- How to open Diia.Card in 2026
- Which banks open Diia.Card
- Diia.Card in monobank: how it works
- Diia.Card in PrivatBank: what to know
- Who can open Diia.Card
- How to use Diia.Card after opening
- Can you keep your own money on Diia.Card
A search for a digital identity card can lead to several different products, but Ukraine's Diia.Card is not a generic electronic ID. It is a bank card designed to receive and manage payments from multiple state programs through one payment instrument. The identity and government-service side is handled through Diia, while the actual card account is opened and serviced by a partner bank.
That distinction is important. Diia.Card does not replace a passport, tax number, or the Diia app. Its main purpose is simpler: instead of opening a separate bank card for every new government payment, a user can connect several special-purpose accounts to one card and keep personal money there as well.
What Diia.Card is and why it differs from a digital identity card
Diia.Card is a multi-account bank card integrated with Ukrainian state-payment programs. One physical or digital card can be connected to a regular personal balance and to several special accounts created for specific benefits.
The idea is to reduce the number of cards people have to open. In older schemes, a new state program often meant another dedicated card. With Diia.Card, the payment instrument stays the same while a new program can add its own account and rules behind it.
The card is opened by a bank, not by the Diia app itself. Diia provides the state-service integration and directs users to a partner bank for the banking product.
Why Diia.Card already has more than 5.8 million users
By August 2026, more than 5.8 million Diia.Cards had been opened. The number of accounts connected to them was even higher, which illustrates the multi-account model: one card can represent several separate balances.
The rapid growth is tied to the expansion of state programs that use Diia.Card. Instead of being useful for only one payment, the card has become a common gateway for child-related support, school assistance, health screening, eBook support, veteran programs, and other targeted payments.
This is why the card is better understood as infrastructure for government payments than as another ordinary debit card.
What payments go to Diia.Card in 2026
The exact list can change as programs are added or redesigned. In 2026, Diia.Card is used for several major schemes, including the Child Care Account, the Baby Package mechanism, the Schoolboy Package, Screening 40+, eBook support, Veteran Sports, and other state initiatives.
Each payment keeps its own eligibility and spending rules. Having a Diia.Card does not automatically make you eligible for every program.
For example, a school-related payment may be restricted to approved categories of goods, while personal money on the same card can be spent like ordinary bank funds.
What is the Child Care Account
The Child Care Account is a dedicated balance inside the Diia.Card system for child-related state support. It is separated from the user's own money so the payment can follow the legal conditions attached to that program.
The key idea is not that one card turns all money into one pool. The card is the shared interface, while the underlying balances remain separate.
That separation matters whenever the government limits where a benefit can be spent or how long it remains available.
Diia.Card and the "Baby Package": how the payment works
In 2026, child-support payments connected with the "Baby Package" can be routed through the appropriate special account linked to Diia.Card. The recipient does not need to open a completely unrelated bank product simply because the payment comes from a different program.
The program itself still determines who qualifies, how much is paid, and what spending restrictions apply. Diia.Card changes the banking layer, not the benefit rules.
If a payment is targeted, you should check whether cash withdrawal, transfers, or purchases outside approved categories are prohibited.
Does the school kit ("Schoolboy Package") go to Diia.Card
Yes. The school kit payment can be credited to a dedicated account connected to Diia.Card. The money remains subject to the rules of the Schoolboy Package rather than becoming unrestricted personal funds.
That means the important question is not only "Did the money arrive?" but also "What can this specific balance be used for?" The bank app may show several balances under one card, and each can behave differently.
How Screening 40+ works through Diia.Card
Ukraine's Screening 40+ program provides UAH 2,000 for an approved preventive health screening. The payment goes to a special Diia.Card account and is used cashlessly at participating healthcare providers.
The UAH 2,000 cannot simply be withdrawn as cash. The account exists specifically to pay for the program service.
This is a good example of why Diia.Card uses separate balances: your own money may be fully flexible, while the Screening 40+ balance is tightly restricted.
How to open Diia.Card in 2026
You can open Diia.Card online through Diia or through a participating bank's app. A typical Diia route looks like this:
Update and sign in to Diia.
Open Services.
Choose Diia.Card.
Select a partner bank.
Continue to the bank's app.
Review and accept the bank's terms.
Create the digital card.
Add any required special account for the state program you plan to use.
You normally do not need a branch visit for the digital card. A physical card is optional and depends on the bank.
Which banks open Diia.Card
As of August 2026, five partner banks were listed for Diia.Card:
PrivatBank;
monobank;
Sense Bank;
Bank Credit Dnipro;
A-Bank.
The core state-payment concept is the same, but bank fees, support, app design, ATM access, and physical-card options can differ.
Before opening the card, confirm that the bank supports the particular special account you need.
Diia.Card in monobank: how it works
In monobank, Diia.Card follows the same multi-account model. The user can open the card in the banking app or select monobank while starting the process through Diia.
The digital card is enough for most state-payment scenarios. A physical version may also be available, but it is not automatically necessary.
The practical advantage for an existing monobank customer is that the state-program balances appear inside an app they already use, while the legal restrictions of those balances remain unchanged.
Diia.Card in PrivatBank: what to know
PrivatBank is also an official partner. The card can be opened online and used with supported state-program accounts.
As with any bank, check current conditions for a physical card, cash withdrawal of personal funds, replacement, support, and other banking services. Those details are controlled by the bank rather than by the Diia app.
For targeted benefits, the state program's restrictions take priority over the ordinary card tariff.
Who can open Diia.Card
Diia.Card is generally available to adult Ukrainian citizens who can complete the bank's identification requirements. A Ukrainian tax number is normally used in the process, although individual banks may have specific procedures for exceptional cases.
Opening the card and qualifying for a payment are two separate things. You can have Diia.Card without qualifying for the Schoolboy Package, Screening 40+, or another specific benefit.
Eligibility is always determined by the rules of the state program.
How to use Diia.Card after opening
Think of the card as one front end with several possible sources of money.
Your own balance works like an ordinary bank account under the bank's terms. A special government balance works according to the program that funded it. Some benefits allow only purchases in defined merchant categories; others may permit more flexible use.
Before paying, check which balance is expected to cover the purchase. This is especially important when several state programs are connected to the same card.
Can you keep your own money on Diia.Card
Yes. Diia.Card includes an ordinary personal account that can hold your own funds. You can generally use that money for purchases, transfers, and cash withdrawals according to the bank's standard rules.
This does not remove restrictions from state benefits stored alongside it. Personal and targeted balances remain separate even though one card can access both.
You also do not need to make Diia.Card your salary card or move all your savings to it just because you use it for state support.
How to withdraw money from Diia.Card
Whether money can be withdrawn depends on which balance it belongs to.
Personal funds can normally be withdrawn under the bank's tariff. Targeted payments may block cash withdrawal entirely. For example, Screening 40+ funding is intended only for the approved screening service.
Before using an ATM, open the banking app and identify the type of money you are trying to access. The word "Diia.Card" by itself does not tell you whether withdrawal is allowed.
How Diia.Card mixed payment works
Mixed payment is one of the useful features of the system. If an eligible purchase costs more than the amount remaining on a targeted account, the card may use the special balance first and cover the difference from your personal funds.
For example, if an approved purchase costs UAH 900 and the relevant state balance has UAH 700 left, the remaining UAH 200 can be taken from your personal balance when the payment setup supports it.
This does not expand what the state money may be used for. The purchase still has to qualify under the program.
Why Diia.Card if you already have a regular bank card
You do not need Diia.Card because ordinary debit cards suddenly stopped working. Its main value is access to multiple state-payment programs without creating a new payment card for each one.
You can keep your existing card for salary, subscriptions, and everyday expenses while using Diia.Card primarily for government services.
For some users, the card may eventually become a normal everyday card as well. That is optional, not a requirement.
Diia.Card vs a regular bank card: what's the difference
The clearest difference is the multi-account integration with state programs.
Personal money | Yes | Yes |
|---|---|---|
State special accounts | Yes | Usually not integrated in the same way |
Several balances behind one card | Yes | Usually one main card account |
Personal transfers | Yes | Yes |
Cash withdrawal of personal funds | Yes, under bank rules | Yes, under bank rules |
Targeted spending restrictions | Yes, for special benefits | Normally no |
Diia.Card is therefore not automatically "better." It is optimized for a different job.
Do you need a new Diia.Card for each payment?
No. Avoiding that exact problem is the point of the system.
A new state program can create or connect a separate special account while the user continues to use the same Diia.Card. This is why the number of accounts can be much larger than the number of cards.
You may still need to activate or select the relevant program account, but you do not normally need a completely new card number for each benefit.
Does Diia.Card replace all old state cards
Not necessarily. The system is expanding, but not every legacy payment mechanism disappears at once. Some programs continue to have separate rules or transition periods.
Do not assume that an instruction from 2025 is still correct, but also do not assume that every old card became invalid in 2026. Check the current rules for the specific payment.
The direction is consolidation, not an instant replacement of every government-linked bank product.
Diia.Card: how to choose the right bank
Choose based on the bank, not only on the Diia.Card name. Compare practical details that affect you:
whether you already use the bank;
app reliability and support;
current card fees;
ATM access;
whether you want a physical card;
whether the required state account is supported;
how easy it is to top up and manage personal money.
There is no single best partner bank for everyone. Existing customers often prefer the bank they already know unless another provider offers a feature they specifically need.
Is Diia.Card safe?
Diia.Card is a bank product, so standard banking-security rules apply. Never give another person your PIN, password, one-time confirmation code, or card security code.
A caller who claims to represent Diia or a bank does not need your one-time code to "release" a state payment. Requests like that are a common sign of fraud.
Use the official Diia app and your bank's official app. If a message contains a payment link, verify it independently rather than trusting the message simply because it uses government branding.
What to check before opening Diia.Card
Before opening the card, answer six practical questions:
Which state program do you need it for?
Are you actually eligible for that program?
Does the program create a special account?
What can the benefit be spent on?
Can any part of the benefit be withdrawn or transferred?
Which partner bank is most convenient for you?
This prevents a common misunderstanding: the card may look like an ordinary debit card, but targeted state money can have very different rules from your own funds.
Diia.Card in 2026: what has really changed
The important change is not the plastic or the digital card image. It is the move toward one payment instrument with multiple separate accounts.
By August 2026, more than 5.8 million people had opened Diia.Card, and the system was supporting millions more accounts than cards. That scale shows why the model is useful: new state programs can be added without forcing every recipient to repeat the whole bank-card setup.
For users, the rule to remember is simple: one card does not mean one type of money. Always check whether you are spending personal funds or a benefit with its own restrictions.
FAQ
What is Diia.Card in simple words?
It is a bank card that can combine a personal account with several special accounts for Ukrainian state payments. It is not a replacement for your digital identity documents.
Why do you need Diia.Card?
Its main purpose is to receive different state payments without opening a completely separate card for every program.
How do you open Diia.Card?
Start in Diia or in a partner bank's app, choose a bank, complete identification and bank terms, and create the digital card. Then connect the special account required by your program.
How do you open Diia.Card in monobank?
You can start in the monobank app or choose monobank when opening Diia.Card through Diia, then complete the bank's digital setup.
Which banks open Diia.Card?
As of August 2026, the listed partners were PrivatBank, monobank, Sense Bank, Bank Credit Dnipro, and A-Bank.
Can you get the "Baby Package" on Diia.Card?
Yes, child-related support can use a dedicated special account connected to Diia.Card. The program's eligibility and spending rules still apply.
Does the school kit payment go to Diia.Card?
Yes. The Schoolboy Package payment is credited to the appropriate special balance and can be used according to that program's rules.
How do you withdraw money from Diia.Card?
Your own money can generally be withdrawn under the bank's rules. Targeted state payments may block cash withdrawal, so check the specific balance first.
Can you transfer money from Diia.Card?
Personal funds can normally be transferred. State-program balances follow the rules of the particular benefit and may restrict transfers.
Can you pay with Diia.Card like a normal card?
Yes when using your personal balance. Targeted balances work only for permitted purchases or services.
Do you need a new Diia.Card for each payment?
No. Multiple special accounts can be connected to the same card, which is the main reason the system exists.
Is Diia.Card the same as the Diia app?
No. Diia is a state digital-service platform. Diia.Card is a bank product opened and serviced by a partner bank.
Best of the week — in your inbox
No spam. Only top Gosta stories. Unsubscribe in one click.
Comments